What If the US 10-Year Crosses 5% — and Refuses to Come Down?
MacroStory Research | 2 September 2026
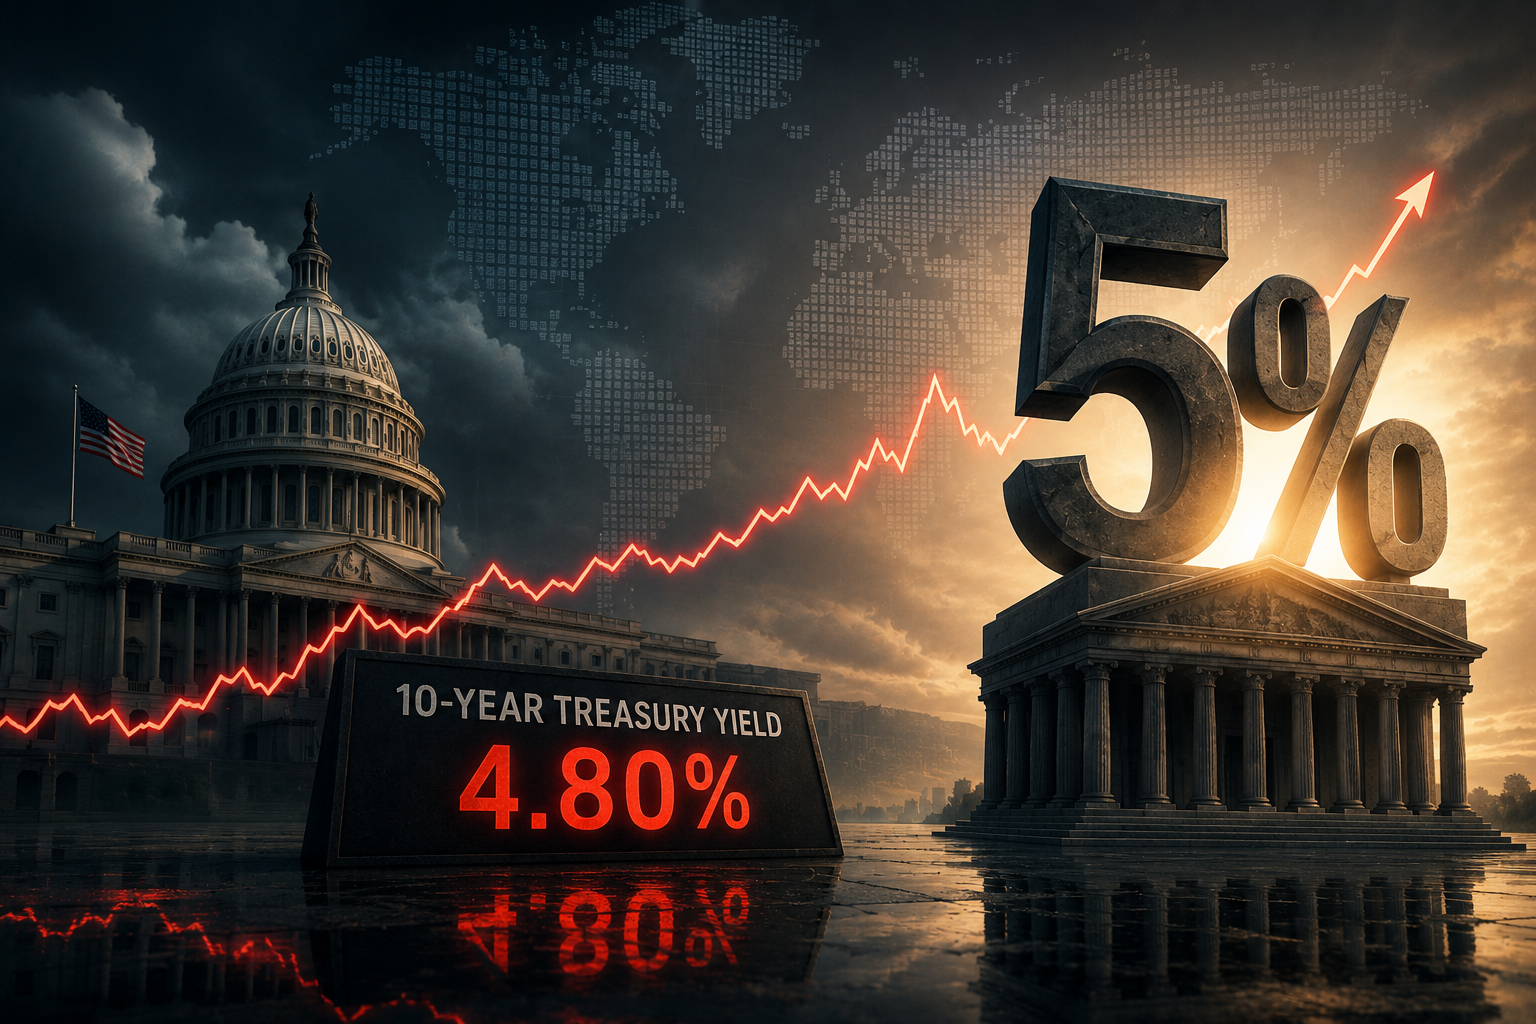
The U.S. 10-year Treasury yield is now around 4.80%, leaving just 20 basis points between today’s market and the psychologically important 5% threshold. But the real question is not whether the 10-year touches 5%. Markets can overshoot. The far more important question is what happens if it reaches 5% and stays there.
That would represent something much larger than another bond-market selloff. A persistent 5% Treasury yield could signal that the global price of capital has structurally shifted higher—and that investors are demanding greater compensation for inflation, fiscal uncertainty and holding long-duration government debt. The 10-year was around 4.20% at the beginning of 2026; at today’s 4.80%, that represents roughly a 60-basis-point increase this year.
The Market Is Moving Faster Than Policy
DataTrek’s latest investor survey offers an interesting backdrop. 58% of respondents expected the 10-year Treasury to finish 2026 around its then-current 4.6% level or higher, while just 42% expected meaningfully lower yields. At the same time, 76% expected no U.S. recession over the following 12 months and 29% expected another 25-basis-point Fed hike by year-end.
That combination is important: resilient growth + sticky inflation + higher policy rates is naturally hostile to long-duration bonds.
But the selloff has already gone beyond those survey levels. The 10-year is approximately 20 basis points higher than the 4.6% level DataTrek referenced, while the 30-year has recently traded above 5.25%.
This is becoming a test for Fed Chair Kevin Warsh. If tighter monetary policy is supposed to restore confidence in long-run inflation stability, eventually long-term yields should respond positively. Instead, Warsh’s hawkish Jackson Hole message has coincided with further pressure at the long end.
That deserves attention.
This Is Not Just a Fed Story
Perhaps the strongest evidence comes from outside America.
Japan’s 10-year yield has reached 3.00% for the first time since 1996. Germany’s 10-year Bund is around 3.35%, its highest since 2011. Britain’s 10-year gilt has climbed to approximately 5.25%, its highest since 2008.
In other words:
US 10Y: ~4.80%
UK 10Y: ~5.25%
Germany 10Y: ~3.35%
Japan 10Y: ~3.00%
This synchronized move tells us something important. Markets are not simply repricing the September Fed meeting. They are repricing global sovereign duration.
Inflation is part of the explanation. Oil has surged again as the Middle East conflict intensifies. Fiscal expansion is another. Governments are simultaneously financing defence, ageing populations, industrial policy and legacy deficits.
Investors are therefore demanding a higher price to lend governments money for 10, 20 or 30 years.
Then Comes the Supply Problem
For Treasury Secretary Scott Bessent, the arithmetic is increasingly uncomfortable.
Treasury expects to borrow $739 billion in privately held net marketable debt during July–September alone, followed by another $628 billion during October–December. Combined, that’s approximately $1.37 trillion in net marketable borrowing in just six months.
September’s planned nominal coupon auctions alone total approximately $315 billion across 2-, 3-, 5-, 7-, 10-, 20- and 30-year maturities. Add a planned $19 billion 10-year TIPS reopening and $28 billion FRN auction, and the scale of securities constantly passing through the market becomes clear.
The issue isn’t whether America can find buyers.
It can.
The question is:
What yield will investors demand to absorb all that supply?
That is a fundamentally different question.
Treasury Has Already Responded
Bessent’s Treasury has not been passive.
Treasury originally planned up to $38 billion of liquidity-support buybacks during the current refunding quarter, plus as much as $25 billion of short-maturity cash-management buybacks. Then, on August 19, it announced that long-end liquidity-support operations would be at least doubled from $2 billion to $4 billion per operation, beginning September 9.
Markets initially celebrated.
But the relief proved short-lived.
After the August announcement, the 10-year subsequently climbed toward 4.8%, while long-end yields again approached their cycle highs. Reuters noted that analysts saw the underlying forces—large fiscal deficits and rising inflation expectations—as far bigger than the impact of the buyback program.
That distinction is critical.
Buybacks can improve liquidity. They cannot eliminate supply.
In fact, Treasury itself explicitly says buybacks are not expected to significantly reduce privately held net marketable borrowing because new issuance replaces the securities Treasury buys back.
That may be the single most important statistic in this debate.
Japan Could Make the Problem Harder
There is another structural development that Washington cannot control.
Japan.
Japanese institutions have historically been major buyers of U.S. Treasuries because domestic yields were extraordinarily low. But Japan’s 10-year now yields around 3%, while its 30-year borrowing cost has moved above 4%.
That changes the relative-value calculation.
Treasury data showed foreign U.S. bond holdings declined in June, led by Japan, Britain and China, with Japan remaining America’s largest foreign Treasury holder.
Japan is not abandoning Treasuries. But American policymakers can no longer assume that enormous pools of foreign savings will automatically absorb additional Treasury issuance at yesterday’s yields.
Higher domestic yields give Japanese capital a reason to stay home.
Why 5% Changes the Equation
A 5% Treasury yield matters because it becomes the benchmark against which almost every risky asset must compete.
Why own a corporate bond yielding 6% if Treasuries offer 5% without corporate credit risk?
Why accept a 4% property yield when financing costs are substantially higher?
Why pay extremely high equity multiples unless earnings growth can comfortably exceed a 5% risk-free hurdle?
The mathematics becomes particularly powerful for long-duration assets.
Consider a simple $100 perpetual annual cash flow.
At a 4% discount rate, its theoretical value is $2,500.
At 5%, its value falls to $2,000.
That’s a 20% decline in theoretical valuation from a one-percentage-point increase in the discount rate.
Real companies are obviously more complicated, but the mathematics illustrates why sustained higher Treasury yields can eventually compress equity multiples even without a recession.
The Dangerous Scenario Isn’t 5%
There are really three possible outcomes.
If the 10-year briefly touches 5%, economic data weaken and yields retreat toward 4.5%–4.7%, then 5% was simply a cyclical overshoot.
If yields reach 5% and remain in a 4.9%–5.2% range, markets may be establishing a new, structurally higher equilibrium cost of capital.
But the third scenario is the one that matters most.
Suppose Warsh remains hawkish. Treasury expands its bond-market operations. Inflation expectations stabilize. Yet the 10-year continues through 5.0%, 5.1% and 5.2%.
At that point, investors would have to consider whether they are witnessing something fundamentally different:
a rising fiscal and term premium.
The bond market would effectively be telling Washington that monetary tightening alone isn’t enough.
The Feedback Loop
This is where persistence becomes dangerous.
Higher yields raise government refinancing costs. Higher interest costs worsen deficits, all else equal. Larger deficits require additional issuance. More supply requires investors to absorb more duration. Investors may then demand a larger term premium, pushing yields higher again.
It looks like this:
Higher yields → Higher interest expense → Larger deficits → More issuance → Higher term premium → Higher yields
This does not mean the United States is facing an imminent sovereign debt crisis.
It means the price of financing the U.S. government can rise considerably without America ever losing access to capital markets.
That distinction is extremely important.
The risk isn’t that buyers disappear.
The risk is that buyers demand 5%, 5.25% or 5.5%.
Our Dashboard
The numbers we would watch now are straightforward:
| Indicator | Current Area | Stress Level |
|---|---|---|
| US 10Y | ~4.80% | 5.00% |
| US 30Y | ~5.25% | 5.30–5.35% |
| Japan 10Y | ~3.00% | Sustained >3% |
| UK 10Y | ~5.25% | New cycle highs |
| Germany 10Y | ~3.35% | Further acceleration |
| US Q3 net borrowing | $739bn | Supply pressure |
| US Q4 net borrowing | $628bn | Supply pressure |
The most important observation is that these variables are moving together.
MacroStory View
The U.S. 10-year crossing 5% would make headlines.
But 5% itself isn’t the real story.
The real story begins if the yield refuses to come back down.
A persistent move above 5% would suggest that markets are no longer merely debating whether Warsh raises rates once or twice. Investors may instead be demanding structurally greater compensation for inflation uncertainty, enormous sovereign issuance and long-duration risk.
And that would explain why the same phenomenon is appearing from Washington to London, Frankfurt and Tokyo.
For Warsh, the challenge is monetary credibility.
For Bessent, it is fiscal and debt-management credibility.
For investors, the question is simpler:
What if 5% isn’t the top—but the new floor?
That would represent something much larger than another Treasury selloff.
It would mean the world’s risk-free rate has been repriced—and almost every financial asset would eventually have to adjust.
Sources: U.S. Treasury, Reuters, DataTrek Research and MacroStory analysis. Data as of 2 September 2026.